
Main
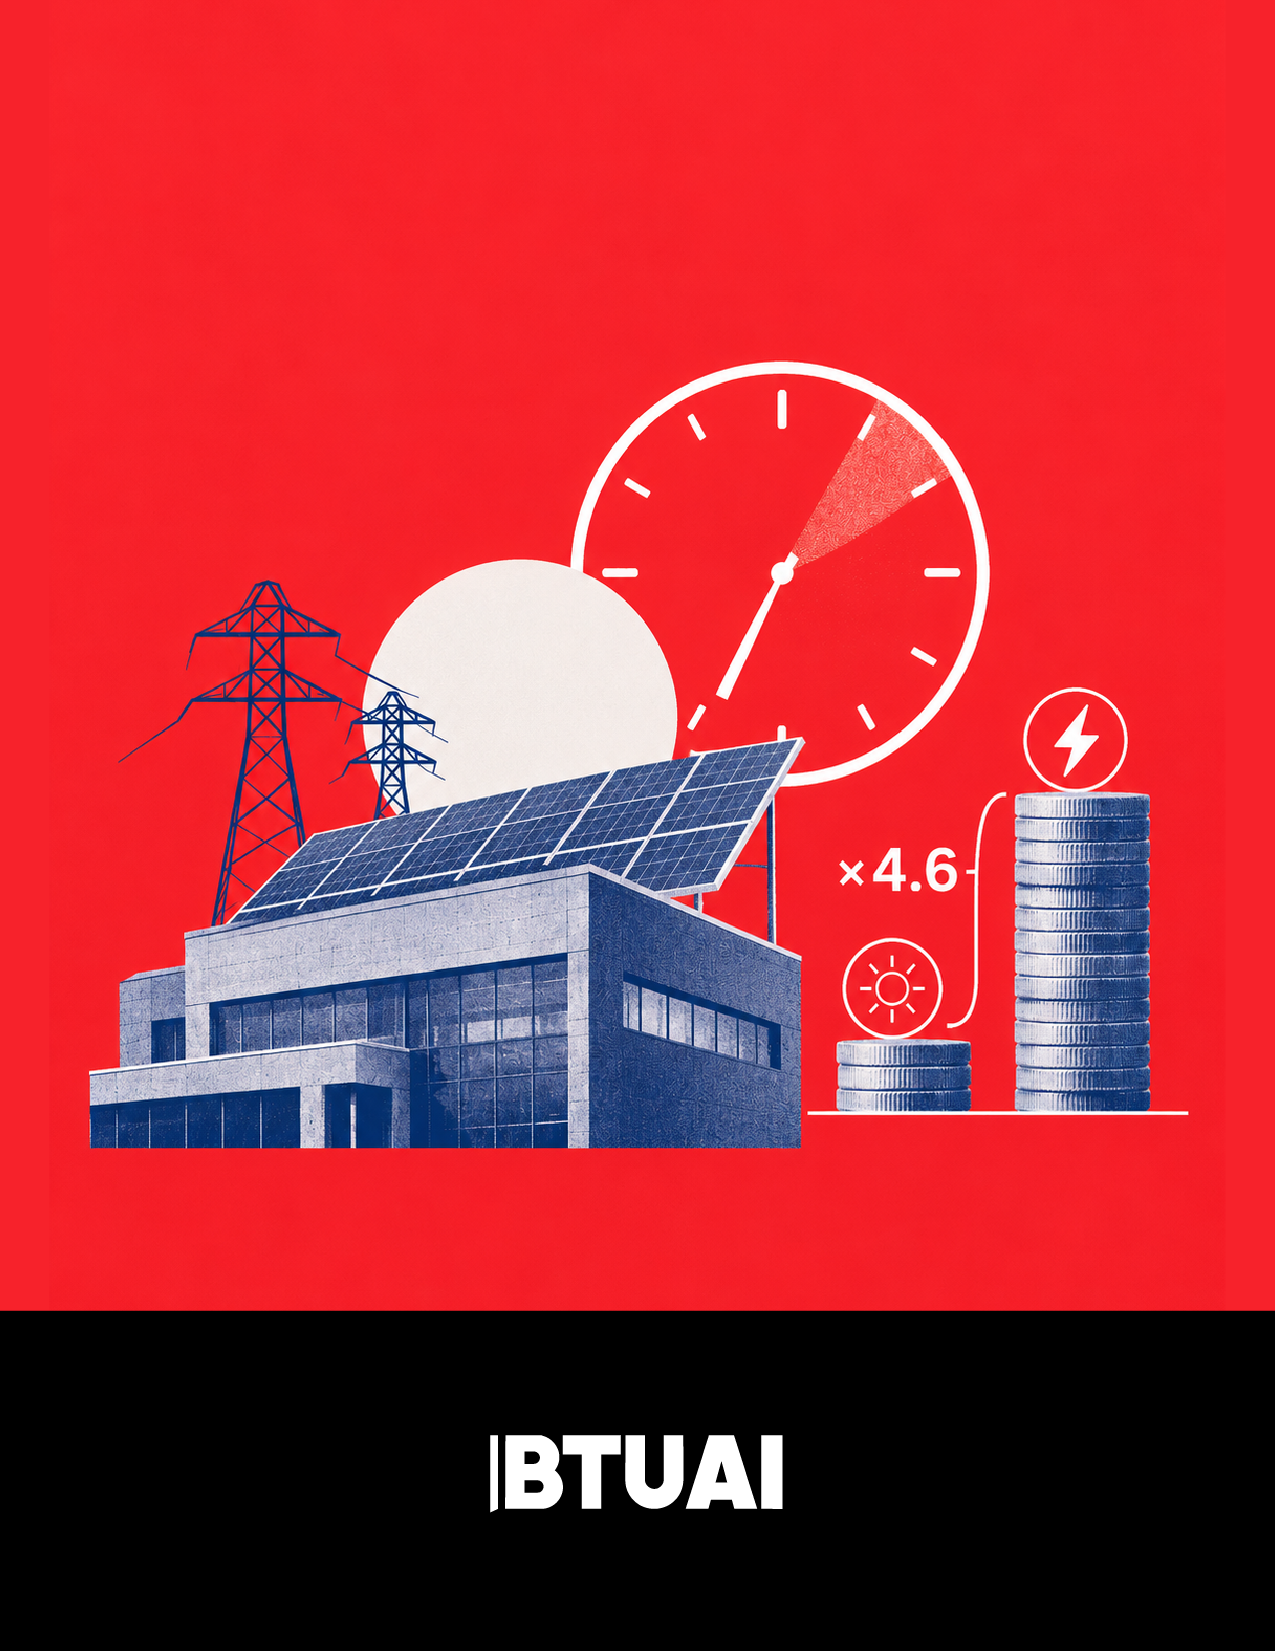
BTU researchers calculate that, under net billing, the tariff avoided by using solar electricity on site is approximately 4.6 times the surplus export price for EP Georgia Supply’s low-voltage non-household customers, excluding VAT. That gap makes operating hours and actual demand more important to the evaluation of a solar project.
Key Takeaways
- At tariffs checked on 26 October 2026, EP Georgia Supply’s 220/380-volt non-household purchase tariff is 30.265 tetri/kWh and its net-billing surplus price is 6.556 tetri/kWh, both excluding VAT.
- BTU researchers calculate a 4.62 ratio between these prices; the comparison concerns alternative uses of each kilowatt-hour, not an investment return.
- BTU researchers assess that Georgian net-billing projects should be evaluated against actual customer load and connection status: higher annual output does not automatically mean greater economic benefit.
A kilowatt-hour generated on a business roof does not necessarily have the same economic value wherever it goes. When the business uses the electricity as it is produced, it avoids buying that quantity from the grid. When it exports surplus electricity under net billing, it receives a separately determined price. The difference changes the investment question: annual generation alone cannot tell an owner what a solar installation is worth.
BTU researchers compared EP Georgia Supply’s low-voltage non-household tariff with its net-billing surplus purchase price. The gap shows how differently a reduction in necessary purchases and a sale of surplus generation affect the customer’s finances. Both prices exclude VAT so that a tax-basis difference is not mistaken for an economic one. [1,2]
The issue returned to the Georgian business agenda in a BM.GE report published on 25 October. Industry participants described weaker interest in projects under the new settlement arrangements. Their comments are useful evidence of business concerns, but not a statistical measure of demand across the entire market. The wider question is how an already adopted rule changes investment choices-and why identical panels can produce different economic outcomes for two firms. [5]
Two prices for one kilowatt hour
The supplier’s published tariff for the specified low-voltage non-household customer is 30.265 tetri per kilowatt-hour, excluding VAT. GNERC, Georgia’s energy regulator, lists 6.556 tetri as EP Georgia Supply’s net-billing purchase price for surplus electricity. The stated validity of that surplus price runs from 1 April 2026 to 1 January 2027. Those figures do not establish what the price will be next year. [1,2]
The tax basis matters. The supplier also lists an inclusive-VAT tariff of 35.7127 tetri. Comparing that amount directly with an export price excluding VAT would artificially enlarge the gap. BTU therefore uses the exclusive-VAT column throughout. The result applies to the identified customer class, rather than every household, every supplier or every voltage level.
EP Georgia Supply low voltage nonhousehold price comparison
| Measure | Value, excluding VAT | Evidence status |
|---|---|---|
| Published grid-purchase tariff | 30.265 tetri/kWh | Supplier figure |
| Net-billing surplus purchase price | 6.556 tetri/kWh | GNERC figure |
| Price difference | 23.709 tetri/kWh | BTU calculation |
| Purchase tariff / surplus price | 4.62 times | BTU calculation; ratio, not profit |
Sources: EP Georgia Supply and GNERC. Checked 26 October 2026. Surplus price: 1 April 2026–1 January 2027. Comparison concerns 220/380 volts and net billing.
The distinction becomes clearer when following the money. Electricity used directly at the business reduces the amount it needs to buy; exported electricity earns a payment or a monetary credit. At these tariffs, the first use has greater value per kilowatt-hour. But its volume is limited by actual consumption. A solar installation cannot be credited with avoiding expenditure that the customer would never have incurred.
Why the annual balance is no longer enough
Net metering and net billing are different settlement mechanisms. The first offsets energy quantities, while the second purchases exported electricity and charges separately for service received from the grid. Put simply, the account records a monetary value rather than an equivalent quantity of electricity available for offsetting. Equal annual generation and annual consumption therefore do not automatically produce a zero electricity bill under net billing. [4]
BTU’s central analytical conclusion follows from that distinction: a solar project’s commercial value becomes more closely connected to the timing of the customer’s electricity needs. High annual consumption can be helpful, but is not a sufficient condition. If much of that consumption does not coincide with solar generation, the business sells surplus output at one price and purchases electricity later at its retail tariff.
Identical roof space and identical installed capacity will consequently not guarantee identical results. A shop, production business or service premises operating during daylight may be able to use some of its generation directly. A business operating mainly in the evening may have a smaller overlap. These examples explain the mechanism; the analysis does not measure actual self-consumption shares in any of those sectors.
Solar energy and business costs
Electricity is an essential input for many Georgian small businesses. Lighting a retail space, cooling products, running workshop equipment and delivering services create different demand patterns. An on-site source may reduce part of the electricity purchase bill, but the outcome depends on how much output the business uses and how much it must export. Technical generation and economically valuable generation are related but distinct considerations.
In BTU researchers’ assessment, the price gap creates demand for better-matched projects, not simply for more panels. A competitive supplier should explain why a particular capacity fits a particular customer’s load. The largest installation is not automatically the best investment. A larger share of the output from additional panels may become surplus sold to the grid. Expansion is not ruled out; its justification changes.
This also creates an opportunity for energy-service businesses that offer more than equipment. Interpreting consumption data, selecting an appropriate system and explaining the expected result become valuable services in their own right. Capturing that opportunity does not require promising the same savings percentage to every client. Showing differences honestly can make an offer more credible and reduce the risk of a customer buying capacity that is poorly suited to its needs.
The composition of the retail price matters as well. The supplier’s low-voltage tariff contains distribution and transmission components alongside supply. The gap between an export price and the full retail tariff is therefore not a measure of the supplier’s profit. Nor does it prove that electricity exported to the grid is worthless. Network use entails service costs. The economics of an individual installation and the allocation of system costs are connected questions, but they are not interchangeable. [2]
Existing connections and new projects need different treatment
Public discussion needs particular precision about transitional arrangements. The law adopted in 2025 provides for relevant existing connections to retain their connection-time conditions until 1 January 2033. Net billing is not solely a distant future change: the rules also cover connections made after the specified network-capacity threshold has been used. The calendar date of buying panels cannot, by itself, establish the settlement regime for an installation. [3,4]
The prices compared here concern a net-billing project; a protected net-metering installation has its own conditions. The start of 2027 does not mean the same change for every existing owner. For an individual buyer, actual connection status and contractual documentation matter more than a generic sales claim.
The same discipline is needed when discussing future prices. A generating installation is a multi-year asset, whereas the export price used here applies to a stated period. Today’s gap reveals the direction of the current incentive, but cannot guarantee future revenue. The renewed public debate is a reason to assess projects more carefully-not proof that solar energy is either profitable everywhere or economically pointless everywhere.
The full cost of a project
The price comparison needs to be combined with the project’s full costs: capital expenditure, financing, technical losses and maintenance. Connecting these items with actual generation and consumption shows whether sufficient benefit remains after costs. Assigning different values to directly consumed and exported electricity is the starting point for that appraisal, rather than its final answer on investment returns.
Changing the timing of consumption can also carry costs. Moving production may affect staffing, delivery commitments or product quality. Possible savings on electricity purchases should not be cancelled out by additional necessary expenditure elsewhere. Storage equipment is a separate investment too; a price gap alone cannot establish whether it pays for itself. This article calculates neither a battery payback period nor a universal solar return.
A high self-consumption share should not become an end in itself. If a business uses extra electricity merely to avoid exporting it, it has not avoided a necessary purchase. Economic benefit arises when generation serves an activity the business actually needs. Efficiency and on-site generation are therefore not interchangeable answers. Understanding necessary consumption and avoidable waste comes first; only then can the owner identify how much solar output will replace purchases and how much will remain for sale.
For Georgia, the important implication is more accurate energy investment. Where two uses of generated electricity have different monetary values, businesses should look beyond annual kilowatt-hours. BTU researchers’ assessment is that the stronger project is the one fitted to actual operations: reducing purchases when electricity is needed, and valuing the remaining output at its real sale price. That makes solar generation an informed part of cost management, rather than the same promise offered to every customer.
Questions and Answers
Are more panels always a better choice?
A greater share of additional generation may become surplus for sale. Expansion needs to be assessed against its incremental cost and actual use.
Why do both prices exclude VAT?
The comparison requires a common tax basis. Comparing an inclusive-VAT purchase tariff with an exclusive-VAT sale price would artificially enlarge the gap.
When does self-consumption become a saving?
When on-site generation replaces necessary electricity the business would otherwise buy. Increasing consumption merely to avoid surplus exports does not create that saving.
What establishes the regime for a specific project?
Actual connection status and contractual conditions. The year panels were purchased is not sufficient to distinguish net metering from net billing.