Key Takeaway
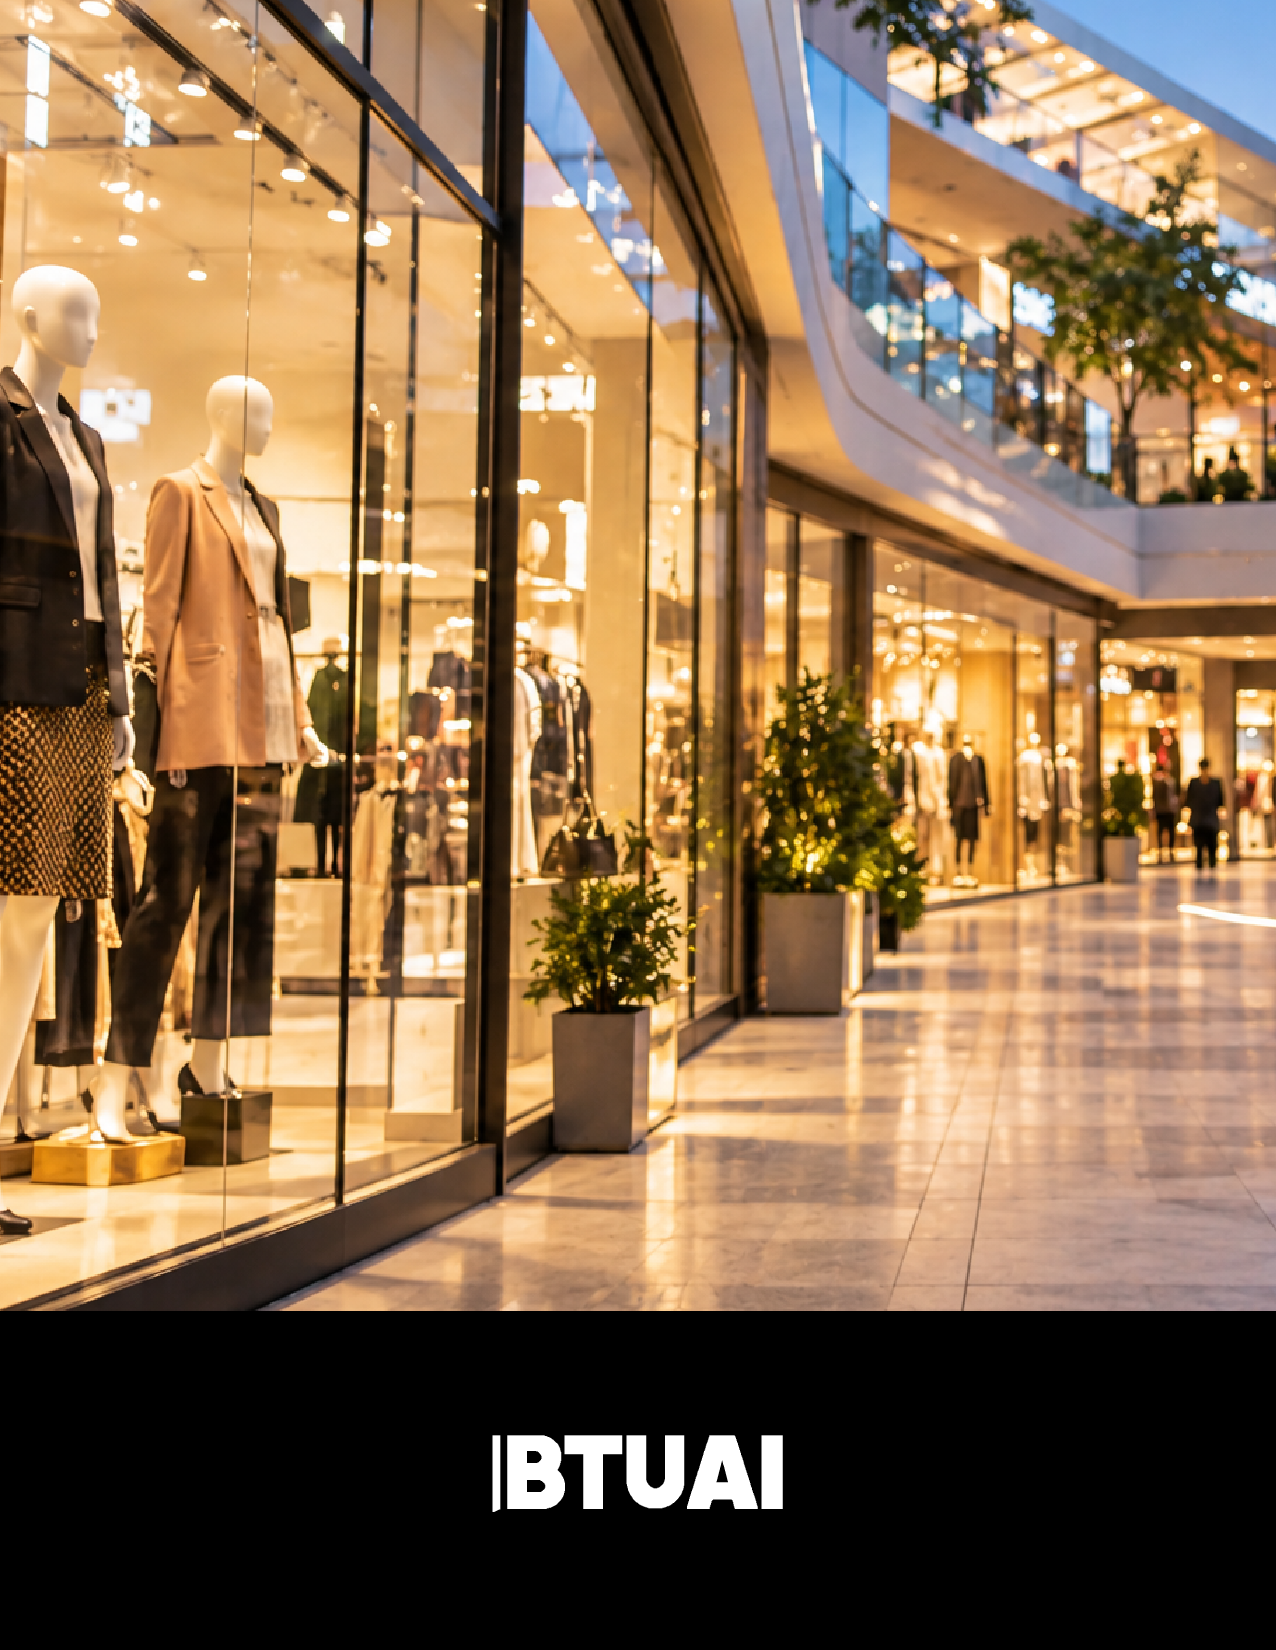
Shopping malls, once treated as one of the clearest casualties of e-commerce and the pandemic, have become the best-performing commercial real estate category in the United States in 2026. The Wall Street Journal, citing Green Street, reports that mall values rose 13% over the past year. Yet this is not a story about e-commerce losing. The malls that are recovering have changed their function: they increasingly combine retail with dining, entertainment, services and social experience.
For Georgia, the lesson is especially relevant because two forces are advancing at the same time: modern retail space is expanding, while e-commerce penetration is rising quickly. The strategic question is therefore no longer whether malls will disappear, but which malls will remain part of consumers’ everyday routines and which will become obsolete.
Why investors are returning
The U.S. recovery has several drivers. Consumer spending has remained resilient, retailer bankruptcies have been limited, and very little new enclosed-mall supply has been added. Scarcity has therefore increased the value of strong locations. At the same time, leading owners have renovated properties and changed tenant mixes toward categories that are less vulnerable to straightforward online substitution, including restaurants, entertainment and selected premium retail.
The WSJ notes that roughly 200 U.S. malls have closed since 2008, leaving about 900 operating. This helps explain the apparent paradox: a significant share of weaker assets has already exited, while the remaining stronger properties face less competition. Simon Property Group reached a new stock-market high in July 2026 for the first time since 2016, while Unibail-Rodamco-Westfield, which had previously planned to retreat from the U.S., committed close to $1 billion to buy out partners at two American malls.
The rebound is not limited to trophy assets. The WSJ highlights West County Center, where tenant sales have risen 13% since 2023 and new restaurant and fashion tenants are being added. The recurring pattern is clear: well-located, renovated and differentiated physical retail can still create substantial economic value.
This is not the defeat of e-commerce
A simplistic reading would be that consumers are moving back from online shopping to physical stores. The evidence points instead to coexistence. Galt & Taggart estimates that e-commerce represented about 8% of retail turnover in Georgia in the first half of 2025, up from 3.6% in 2021, and projects penetration of roughly 13.1% by 2030.
That changes the role of physical retail. Consumers no longer need a mall simply to find a product, compare prices or place an order. A successful mall must provide reasons that a screen cannot fully replace: trying products, eating out, entertainment, family time, services, events, meetings and a comfortable public environment.
The modern mall is therefore becoming a platform rather than merely a building. Digital ordering, in-store pickup and returns, loyalty systems, personalized offers and visibility of store inventory can connect the online and offline channels. E-commerce becomes part of the mall ecosystem rather than an external enemy.
What the Georgian market shows
According to Georgia’s National Statistics Office, Geostat, turnover in the broad trade sector reached GEL 21.9 billion in the second quarter of 2026, compared with GEL 19.9 billion a year earlier. According to calculations by BTU researchers, this represents nominal year-on-year growth of approximately 10.1%. The indicator covers more than retail trade and certainly more than shopping malls, so it should not be interpreted as mall-sales growth. It does, however, show that the broader trading environment is not weak.
The real estate structure is also notable. Public market materials compiled by Galt & Taggart indicate that shopping malls accounted for about one quarter of Tbilisi retail space in 2024. Five major malls represented 57% of modern shopping-centre gross leasable area, while a meaningful pipeline of new space is planned for the rest of the decade.
This is both an opportunity and a warning. One reason for the U.S. revival is the shortage of new mall supply. In Tbilisi, additional projects mean that simply adding more square metres is not a strategy. Competition will increasingly depend on concept, location, transit access, parking, tenant quality, food and entertainment, service standards and visit frequency.
Why Georgia cannot copy the U.S. model
The American experience is a useful signal, not a ready-made template. Household income, city scale, car dependence, the depth of investment capital and the number of large retail brands all differ materially from Georgia. A premium-heavy or entertainment-intensive model that works in a major U.S. metropolitan area will not work automatically in every Georgian location.
In Georgia, the more important question is whether the project fits its actual catchment area. Colliers Georgia’s Samgori Mall concept, for example, is built around direct access to the metro, railway and bus connections and emphasizes everyday needs, food and apparel. That logic is very different from a central-city, tourism-oriented or premium retail destination.
The gap between Tbilisi and regional cities also matters. The capital concentrates population, jobs, tourism and purchasing power. A regional project may need a smaller and more practical format, combining a supermarket, pharmacy, food, children’s space, banking and services rather than copying the tenant mix of a large Tbilisi destination.
Where the opportunity lies for Georgian business
The transformation of malls creates opportunities beyond property development. Experience-led centers need differentiated cafés, local brands, entertainment services, health and beauty providers, sports concepts, pop-ups and seasonal events. These categories benefit from the advantages of physical space and are harder to replace with cross-border e-commerce.
A second opportunity is omnichannel retail. A Georgian retailer with both a store network and online sales can use the mall not only as a point of sale but also as a showroom, consultation venue, pickup point and returns hub. In that model, e-commerce does not automatically cannibalize the store; the store becomes infrastructure for digital sales.
A third opportunity is better use of data. Footfall, visit duration, parking use, event performance and category interaction can help managers shape tenant mix and space more effectively. In a relatively small market such as Georgia, mistakes in concept are expensive, which makes evidence-based decisions more important than simply maximizing buildable area.
The main risk: too much space with an old model
The biggest risk is that developers interpret the U.S. comeback as a generic argument for building more malls. The American revival is partly the result of constrained new supply and the exit of weak assets. Georgia faces a different combination: new projects, rising e-commerce and a smaller consumer base.
According to an assessment by BTU researchers, the key competitive battle in Georgia is likely to be less about malls versus online stores and more about high-quality versus low-quality physical retail environments. Strong malls will integrate digital channels, continually refresh tenant mixes and provide a reason to spend time on site. Weak properties that remain collections of shops will face pressure from both e-commerce and newer physical projects.
Conclusion
Shopping malls are returning, but not in their old form. The U.S. experience shows that physical retail gains value when it stops trying to compete with the internet only on assortment and price. The successful mall becomes an environment where shopping, dining, entertainment, services and social experience reinforce one another.
For Georgia, this is an important signal but not proof that more retail space is automatically more profitable. With e-commerce penetration rising and new projects entering the market, selection will become harsher. The next-generation winner will not necessarily be the largest mall, but the one with the clearest purpose, strongest location, best tenant mix and most effective connection to digital commerce.
Data and Main Sources
The Wall Street Journal, “Malls Were Left for Dead. Now They Are the Top Performer in Commercial Real Estate,” 15 September 2026.
National Statistics Office of Georgia (Geostat), Trade – Declarated Data, 2025–2026.
Galt & Taggart, E-commerce in Georgia, 29 December 2025.
Galt & Taggart / Silk Real Estate public offering materials, Tbilisi retail space structure and shopping-centre pipeline.
Colliers Georgia, Samgori Mall project information.
Prepared by the academic team of Business and Technology University and the BTUAI Research Team, Tbilisi, Georgia.